
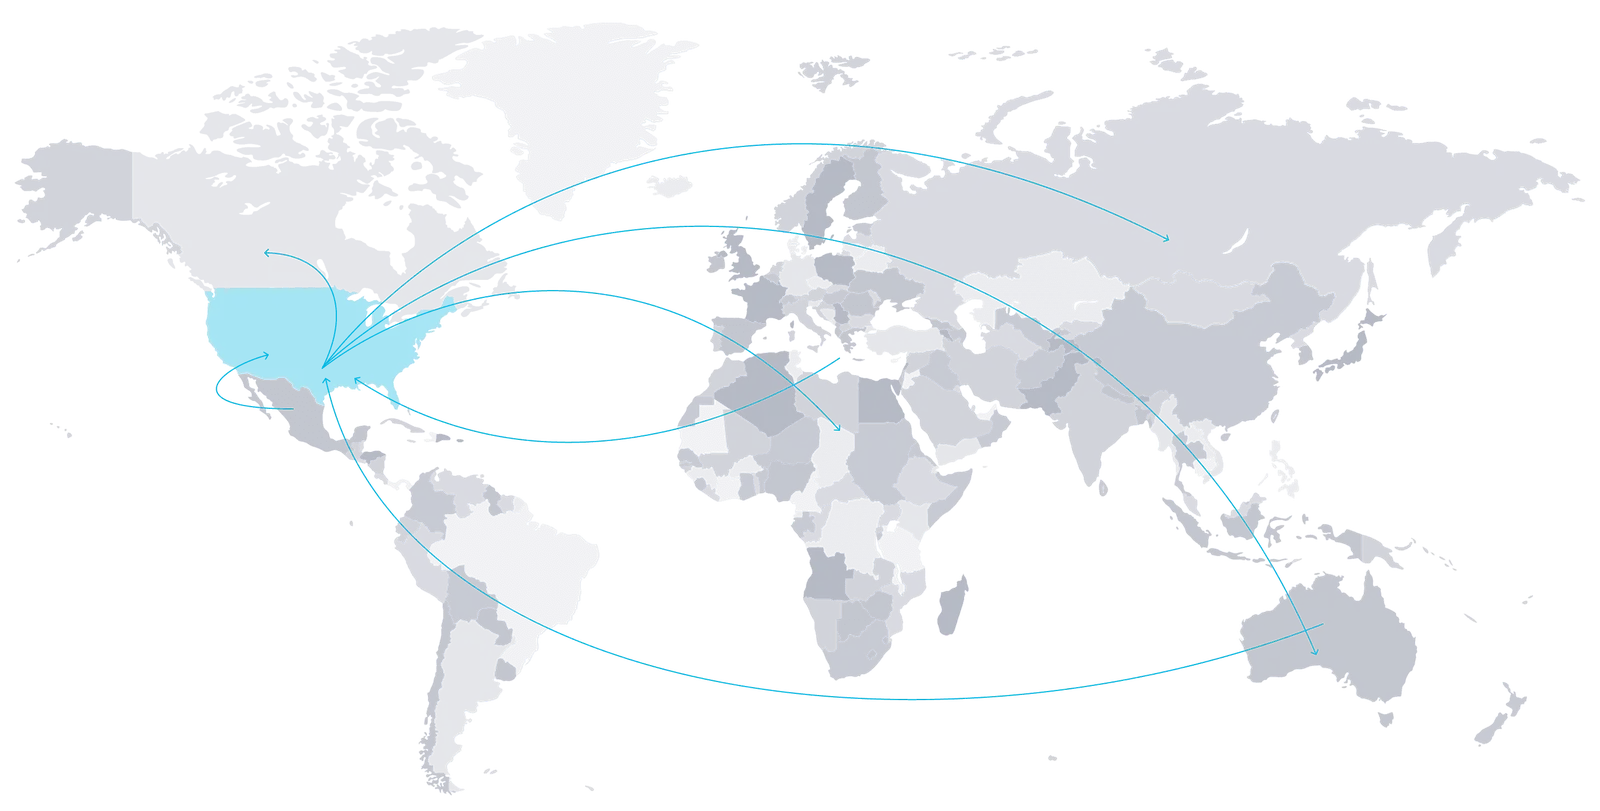
Choose the services that fit you:
Businesses: foreign companies investing in the U.S., and U.S. companies operating abroad
Individuals & Families
Specialized Services: NCTI planning, FIRPTA, and cross-border structuring

Choose the services that fit you:
Businesses: foreign companies investing in the U.S., and U.S. companies operating abroad
Individuals & Families
Specialized Services: NCTI planning, FIRPTA, and cross-border structuring
We help foreign companies and investors enter the U.S. market with the right structure from day one and stay compliant as they grow.
Foreign-Owned U.S. Companies. We prepare Form 5472 for U.S. corporations that are 25% or more foreign-owned and for U.S. LLCs wholly owned by a foreign person. Penalties for missing this form are significant.
Foreign Corporations Doing Business in the U.S. We prepare Form 1120-F for foreign corporations with U.S. business income.
Withholding on Payments to Foreign Persons. We help U.S. companies withhold correctly on payments such as dividends, interest, royalties, and service fees to foreign persons, and prepare Forms 1042 and 1042-S.
U.S. Market Entry. From entity formation to ongoing tax compliance, we help you set up a U.S. structure that fits your business. See Entity Formation & Compliance.
When a U.S. business expands overseas, every foreign subsidiary, branch, or partnership brings new U.S. reporting obligations and tax planning opportunities.
Foreign Subsidiary Reporting. We prepare Form 5471 for foreign corporations, Form 8858 for foreign disregarded entities and branches, and Form 8865 for foreign partnerships.
NCTI Compliance and Planning. We calculate NCTI on Forms 8992 and 8993 and plan to reduce its impact. See NCTI Tax Planning.
Foreign Tax Credits. We prepare Form 1118 to help U.S. corporations claim credit for foreign taxes paid and avoid double taxation.
Overseas Structuring. We compare structures for your foreign operations, including entity classification elections, so that profits are taxed efficiently in both countries.
Moving to the United States or holding assets abroad brings U.S. tax and reporting obligations that many people don't know about until they receive a penalty notice. We help you stay compliant and plan ahead.
Pre-Immigration Tax Planning. Before you become a U.S. tax resident, there is often a window to restructure assets, realize gains, or reorganize foreign companies to reduce future U.S. tax. We help you use that window.
Foreign Account and Asset Reporting. We prepare FBAR (FinCEN Form 114) and Form 8938 to report your foreign bank accounts, investments, and other financial assets.
Owners of Foreign Companies. If you own 10% or more of a foreign company, you may owe U.S. tax on its income each year, even if nothing is distributed. We prepare Form 5471, calculate your NCTI, and analyze whether a Section 962 election can reduce your tax. See NCTI Tax Planning.
Foreign Gifts, Inheritances, and Trusts. If you receive gifts or inheritances from abroad, are involved with a foreign trust, or are a nonresident with U.S. assets, see Estate, Gift & Trust Tax.
Nonresident Tax Returns. We prepare Form 1040-NR for nonresidents with U.S. income, such as rental income, investment income, or income from the sale of U.S. property.
Expatriation and Exit Tax. If you plan to give up U.S. citizenship or a long-term green card, we help you determine whether the exit tax applies and prepare the required filings.
NCTI Tax Planning. The 2025 tax law replaced GILTI with NCTI starting in 2026. If you own a foreign company, directly or through a U.S. company, we help you understand the new rules and choose the most tax-efficient structure. Learn more.
FIRPTA. When a foreign person sells U.S. real estate, the buyer generally must withhold up to 15% of the sale price. We prepare Forms 8288 and 8288-A and apply for reduced withholding with Form 8288-B when the actual tax will be lower, so that sellers are not left waiting for a refund.
Cross-Border Structuring. For families and businesses with interests in more than one country, we design ownership structures that coordinate U.S. tax with foreign tax, from the first investment through future distributions and succession.
| Form | Purpose | Businesses | Individuals |
|---|---|---|---|
| FBAR (FinCEN 114) | Report of foreign bank and financial accounts | ✓ | ✓ |
| Form 8938 | Statement of specified foreign financial assets | ✓ | ✓ |
| Form 5471 | Information return for foreign corporations | ✓ | ✓ |
| Form 8865 | Information return for foreign partnerships | ✓ | ✓ |
| Form 8858 | Information return for foreign disregarded entities and branches | ✓ | ✓ |
| Form 8992 | NCTI calculation | ✓ | ✓ |
| Form 8993 | Section 250 deduction | ✓ | ✓* |
| Form 1118 | Foreign tax credit for corporations | ✓ | |
| Form 5472 | Information return for foreign-owned U.S. companies | ✓ | |
| Form 1120-F | U.S. income tax return for foreign corporations | ✓ | |
| Forms 1042 / 1042-S | Withholding on U.S.-source payments to foreign persons | ✓ | |
| Forms 8288 / 8288-A / 8288-B | FIRPTA withholding and withholding certificate applications | ✓ | ✓ |
| Forms 3520 / 3520-A | Foreign gifts, inheritances, and foreign trusts | ✓ | |
| Form 1040-NR | U.S. income tax return for nonresidents | ✓ |
*For individuals who make a Section 962 election.
We offer cross-border audit, tax, and consulting services for clients across the globe, helping businesses navigate international challenges, ensure compliance, and optimize resource allocation.
Cross-border tax strategies customized to maximize efficiency.
From entity registration to tax compliance, we support your U.S. market entry.
Global experience combined with local market understanding.
We streamline complex international transactions and reduce compliance risk.
 China's Offshore Trust Rules and U.S. Tax: Four MismatchesChina's 2026 offshore trust rules and U.S. foreign trust rules can reach one structure in different years, for different people, on different bases.
 FIRPTA: Turning 15% Withholding on U.S. Real Estate Into 0%FIRPTA is a cash-flow problem disguised as a tax problem. How the 15% withholding works when a foreign owner sells U.S. property, the three ways to manage it, and when the §351 route earns its complexity.
 Portfolio Interest: 30% U.S. Withholding Down to 0%The portfolio interest exception lets a foreign lender receive U.S. interest with zero withholding, no treaty required, if eight conditions are met at origination. The checklist, a worked example, and the failures that only surface in audit.Portfolio Interest: 30% U.S. Withholding Down to 0%The portfolio interest exception lets a foreign lender receive U.S. interest with zero withholding, no treaty required, if eight conditions are met at origination. The checklist, a worked example, and the failures that only surface in audit.FIRPTA: Turning 15% Withholding on U.S. Real Estate Into 0%FIRPTA is a cash-flow problem disguised as a tax problem. How the 15% withholding works when a foreign owner sells U.S. property, the three ways to manage it, and when the §351 route earns its complexity.
 The U.S. Startup Tax Trilogy: Enter, Expand, ExitEntity choice, multi-state nexus, and the QSBS exit exclusion. The three tax decisions every U.S.-market entrant makes, usually in the wrong order, with 2025–2026 thresholds.
Not sure which forms apply to you? Contact us at 310-997-0995 or info@360cpacorp.com for a consultation in English or Chinese.